205 Golf Aire Blvd, Haines City: When a Cash Offer Did Not Fit the Seller’s Goals
Purchased: July 23, 2025
A move motivated by family needs
A daughter and her mother co-owned 205 Golf Aire Blvd. They wanted a newer property nearby and a better home for the elderly mother. The existing house required ongoing maintenance spending, even though the work involved light updates and general upkeep rather than a major renovation.
Why a standard cash purchase did not work
The property had an existing first mortgage, a HUD-related second mortgage lien and a water-treatment lien. Together, those obligations left insufficient room for a conventional discounted cash purchase that would also meet the sellers’ goals.
We discussed that limitation openly. The question was not simply what the house was worth: the liens, financing and sellers’ next housing plans all mattered.
The purchase used existing financing
The property was purchased on July 23, 2025, using a short-term existing-financing arrangement. The sellers received the agreed cash at closing. The buyer accepted responsibility for the property’s carrying and update risks, along with the risk of a later exit or resale.
This arrangement should not be read as a release of the original borrower or a claim that transferring title automatically resolved every obligation. The specific financing and lien arrangements mattered.
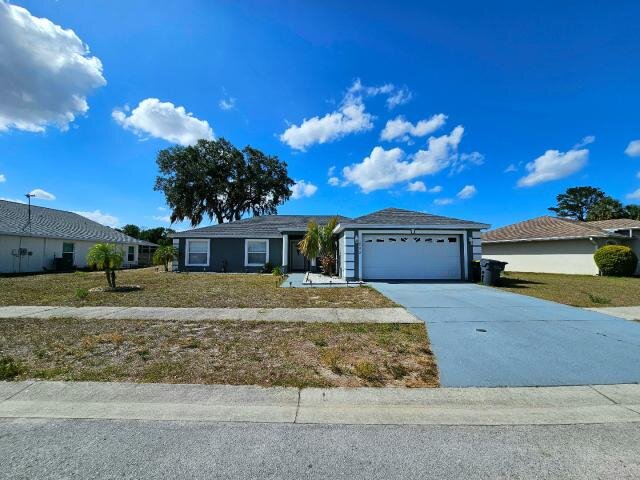
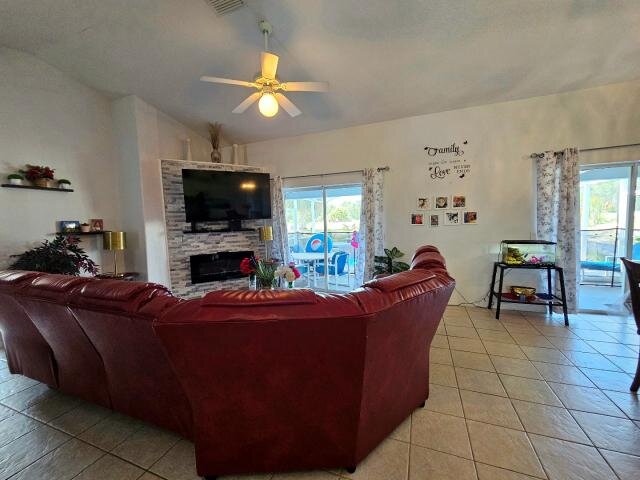
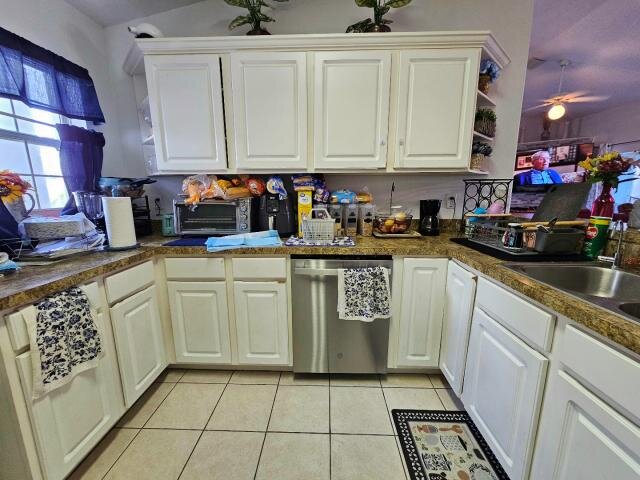
Original property photographs
What this example shows
The sale helped the sellers move toward replacement housing for the mother. A standard all-cash offer was not the best fit. A different structure made this transaction workable for both sides because it accounted for the sellers’ obligations and goals as well as the buyer’s costs and risk.
That does not make existing financing the right answer for everyone. If the mortgage and selling costs leave limited room, start by understanding your low-equity selling options and comparing a direct offer with listing.
Explore more selected Florida case studies or learn about selling a property in Florida.
Talk through your property and goals
Request a no-obligation property review. We can discuss the property, timing and obligations before deciding whether a purchase may make sense.