Sell a House With Low Equity
A house can be in good condition and still be difficult to sell conventionally when the mortgage payoff, commissions, concessions, repairs or other selling costs leave limited room. House For Cash reviews the property and the seller’s circumstances individually.
Talk Through Your Property (407) 214-0772
Real properties. Relevant seller situations.
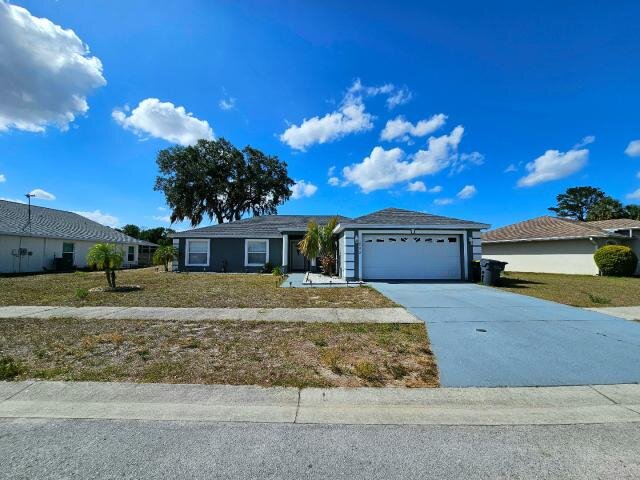
205 Golf Aire Blvd, Haines City, FL
Mortgage and liens affected the options
The mortgage, a HUD-related second lien and a water-treatment lien limited the room for a discounted cash purchase. The agreed purchase used existing financing to support the sellers’ next housing plans; the specific obligations and written terms mattered.
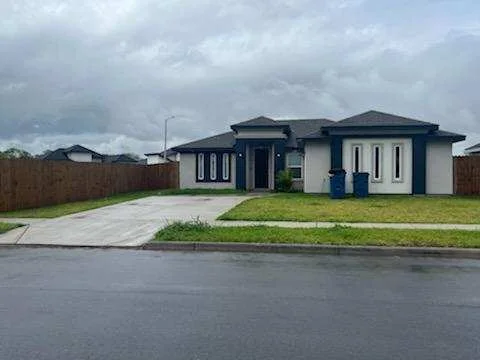
Read the full case study623 Marrs Avenue, Brownsville, TX
Good condition, constrained sale economics
The home was in good condition, but the remaining financing and selling costs left limited room. The completed purchase used existing financing. That did not establish a borrower release or fixed loan-payoff date.
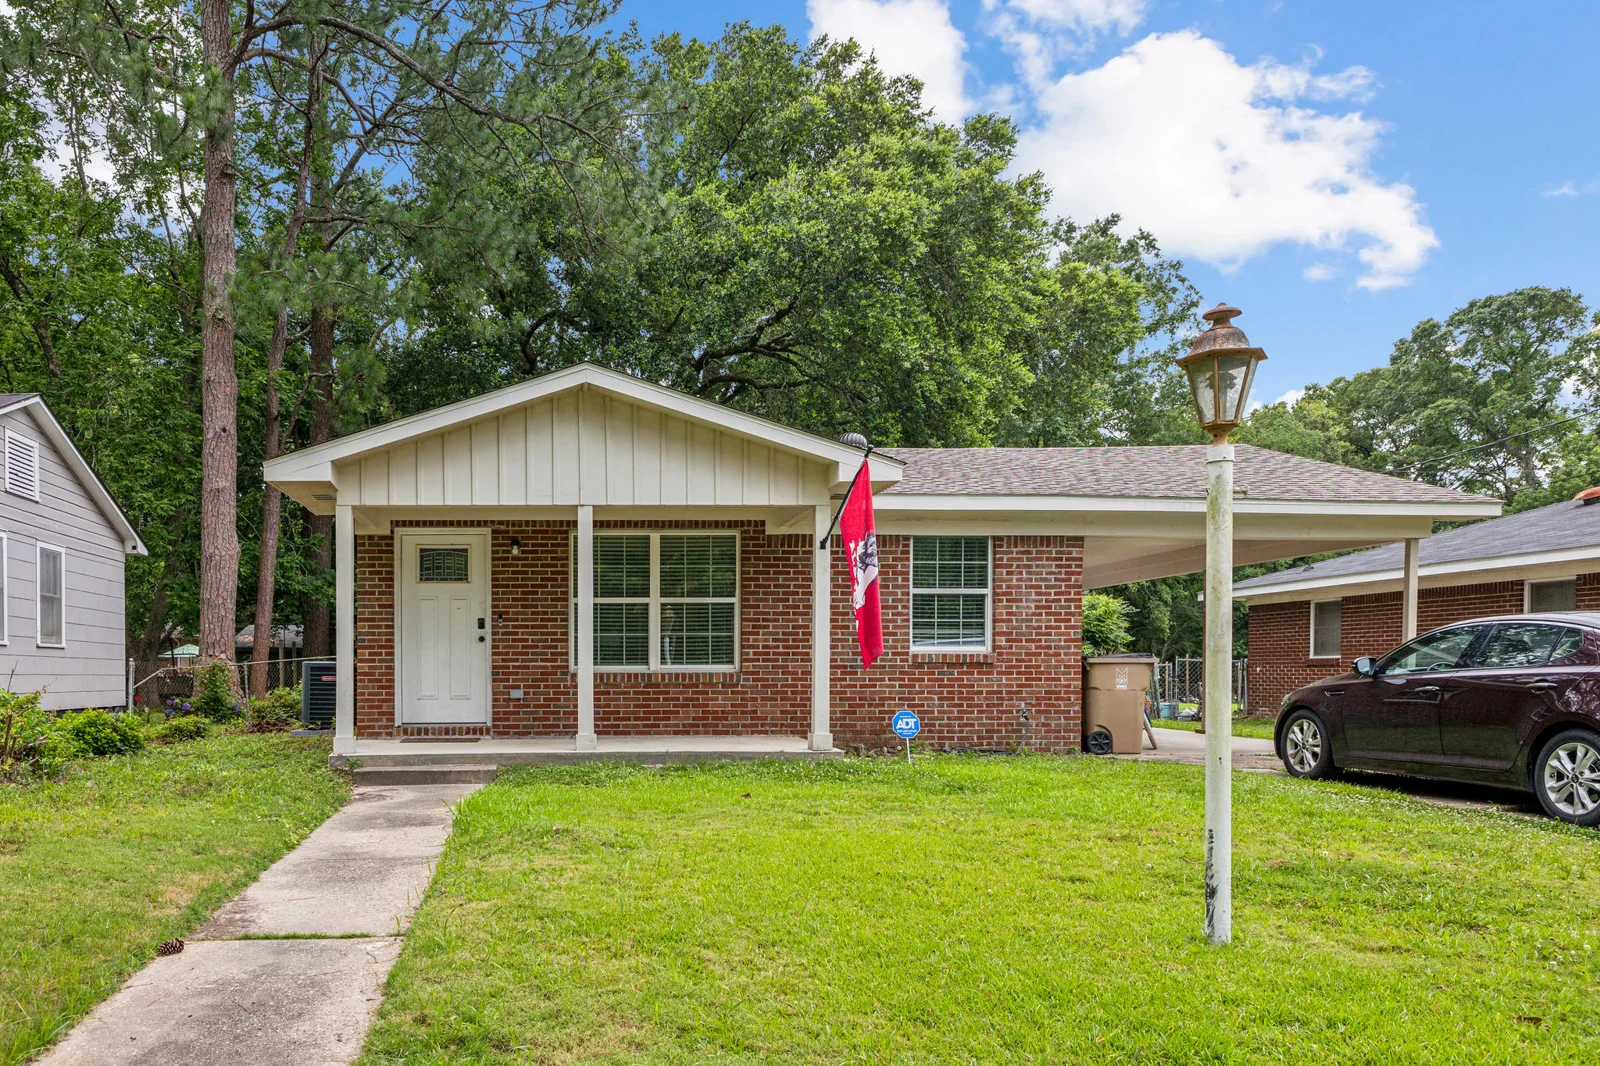
Read the full case study2405 Howell Avenue, Mobile, AL
A rental, relocation and limited equity
The seller was managing an occupied rental after moving for work. Financing and limited equity constrained a conventional sale. It sold with the tenant in place and existing financing remaining; no borrower release or fixed payoff date is implied.
Read the full case studyTalk Through Your Property (407) 214-0772
What matters in this situation
Mortgage balance plus selling costs can affect which options work even when a home is in good condition. A cash offer may not solve every situation. Existing-financing arrangements have separate terms and responsibilities; they do not automatically release the original borrower.
Your next steps
1. Share the situation
Tell us about the property, timing and what you want to accomplish.
2. Review written options
We review the condition, obligations and local market, then explain any purchase proposal that may fit.
3. Decide whether to proceed
Compare the terms and responsibilities. You are not obligated to sell; any closing follows the written agreement and its conditions.
Tell us about your property and plans
Start with the location and how to reach you. Financing and transaction details can be discussed privately during the review.
Real examples across four states
Our completed transactions include owners who were current on payments, an owner with missed payments, people relocating and an owner managing a rental from a distance. Read about House For Cash and the linked case records below.
Limited equity is not the same as missed payments
Equity and expected sale proceeds are related but different questions: selling costs can reduce the room available in a transaction. Limited equity does not establish zero equity, and neither label establishes whether mortgage payments are current. A review should use the actual payoff, other obligations, likely selling costs and property condition rather than assumptions.
A repair-needed home can add preparation costs. A newer, good-condition home can have tight sale economics too. Relocation and tenant occupancy add practical considerations of their own.
Selected completed transactions
The owner had relocated for work and was managing a rental from a distance. Limited equity, relatively low rent and an approaching lease end shaped the situation. The property sold with the tenant and existing financing in place in July 2024. Payment status is not specified in this case.
The home was in good condition. After exploring agent, traditional-sale and investor options, the seller completed a transaction using existing financing in April 2024. The case documents constrained sale economics without an exact equity or payoff amount.
A relocation to family in Florida involved a generally good-condition home, limited equity and missed mortgage payments. The transaction included catching up the delinquency. Leaving financing in place was a separate part of the arrangement; it was not itself the action that resolved the missed payments.
The seller was current on payments and relocating to Texas for his spouse’s work. The newer home and high financing relative to its purchase created different constraints from a delinquent-property sale. Existing financing remained in place in the completed June 2024 transaction.
A newer turnkey home had not sold through a listing. The seller wanted a larger home closer to family, while the remaining balance and selling costs constrained the move. The August 2024 transaction used existing financing. The case does not establish missed payments.
A first mortgage, a HUD-related second mortgage lien and a water-treatment lien left too little room for a standard discounted cash purchase that met the sellers’ housing goals. The July 2025 purchase used a short-term existing-financing arrangement. The case shows why the obligations and agreed terms mattered alongside the property’s condition.
Explore the broader transaction records for Alabama, Texas, Oklahoma and Florida.
A Virginia example, 14388 Fontaine Ct in Woodbridge, shows why good condition does not guarantee room for a discounted cash sale. Limited equity, mortgage arrears and relocation goals shaped a written existing-financing purchase; arrears required separate action.
Compare options and understand the actual terms
When proceeds would not satisfy the required payoff, explore the short-sale process and approval requirements. Limited equity alone does not establish eligibility.
A standard cash offer may not leave enough to cover the mortgage payoff and other required obligations. We look at the actual numbers, your timing and your goals before discussing whether a purchase could work for both sides. A different structure is not automatically a solution.
A conventional listing, a direct purchase proposal or a different timetable may deserve consideration depending on the property and your circumstances. The examples above do not make an existing-financing arrangement the only solution or a promise for another seller.
Leaving a mortgage in place does not itself release the borrower, cure a delinquency or stop foreclosure. Do not assume a fixed payoff deadline from these examples. The specific financing obligations, payment handling and closing terms need to be understood for the individual transaction.
For a broader look at price, selling costs and timing, compare a cash offer with listing through a Realtor.
Three steps
- Share the property’s location, condition, occupancy and your plans.
- Review the relevant payoff, obligations, payment status and proposed terms privately with the people handling the transaction.
- Decide whether a proposed purchase fits your alternatives. Any closing follows the agreement and its required conditions.
Discuss your situation
Use the property form above for an individual review. You can also explore selling when relocating or selling as-is.