Can You Sell Your House Before Foreclosure?
Falling behind can make a home sale feel urgent, even when the property is in good condition or has equity. House For Cash reviews properties and seller circumstances across multiple states. If selling is the right option, a completed sale may resolve a pending foreclosure when it closes in time and the required mortgage payoff, liens and closing obligations can be satisfied.
Talk Through Your Property (407) 214-0772
Real properties. Relevant seller situations.
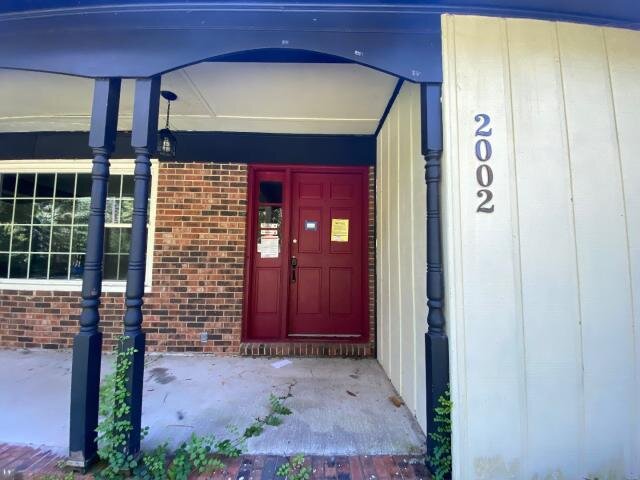
2002 Pinewood Terrace, Fayetteville, NC
Missed payments were addressed separately
The seller was about seven months behind and had lender warnings. The existing-financing purchase included catching up and reinstating arrears. Transferring ownership did not itself cure the default, and the original borrower was not automatically released.
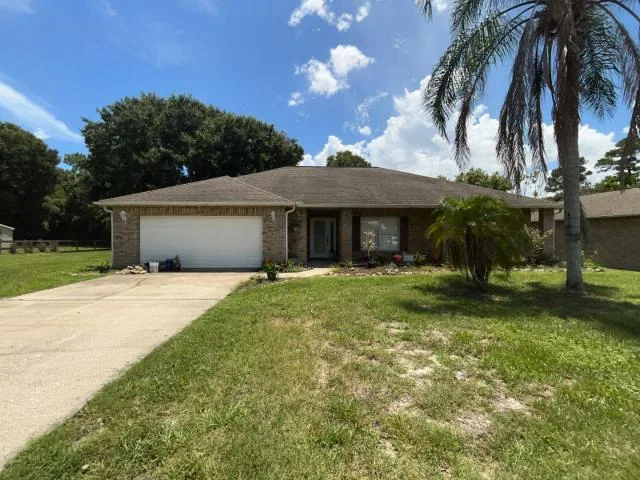
Read the full case study3010 Folsom Rd, Mims, FL
An inherited home and its contents
The family was handling a dated inherited house with belongings and work materials remaining. The mortgage was behind. The property sold as-is; no particular foreclosure filing or auction date is established.
Read the full case studyTalk Through Your Property (407) 214-0772
What matters in this situation
Deadlines matter. A completed sale may resolve a pending foreclosure if it closes before the foreclosure sale and the required mortgage payoff, liens and closing obligations are satisfied. If proceeds are insufficient, lender approval such as a short sale may be required. Requesting an offer or signing a contract does not stop foreclosure.
Your next steps
1. Share the situation
Tell us about the property, timing and what you want to accomplish.
2. Review written options
We review the condition, obligations and local market, then explain any purchase proposal that may fit.
3. Decide whether to proceed
Compare the terms and responsibilities. You are not obligated to sell; any closing follows the written agreement and its conditions.
Request a no-obligation property review
Tell us where the property is and how to reach you. Let us know about any scheduled sale or other deadline when we speak. Requesting an offer does not pause a foreclosure or extend a deadline.
What foreclosure pressure can look like
A loss of income, unpaid rent or a change in household circumstances can make payments difficult. Some owners have missed payments without a documented foreclosure filing; others have received notices or a scheduled sale date. Those situations should not be treated as interchangeable.
Mortgage debt is not the only potential source of pressure. Unpaid HOA obligations, property taxes or other liens may involve separate processes. State laws, lender timelines, HOA processes and tax-sale procedures vary. Review the actual notices with an appropriate professional.
Can you sell before foreclosure?
A completed sale may resolve a pending foreclosure if it closes before the foreclosure sale and the required mortgage payoff, liens and closing obligations are satisfied. A signed purchase agreement alone does not stop a foreclosure. The transaction must close in time, and the amounts required to complete the sale must be satisfied. If the proceeds are insufficient, lender approval such as a short sale may be required.
The available time, ownership, required approvals, title issues and amounts owed all matter. Do not assume that a purchase can close before a deadline until the people handling the transaction have reviewed its requirements.
Common situations homeowners bring to us
- Missed mortgage payments after a job loss or another financial change.
- A rental with nonpaying tenants and ongoing ownership costs.
- Repairs that make preparing for a conventional listing difficult.
- Limited room after payoff and selling costs, or an empty home that still needs attention.
Explore selling without completing repairs, limited-equity sale considerations or options for a vacant home when those circumstances apply.
Options homeowners may consider
The appropriate option depends on the loan, property, finances and time available. Contact your mortgage servicer promptly about payment difficulties. Options to discuss may include:
- Reinstatement: bringing the loan current under the applicable requirements; confirm the amount, deadline and availability with the servicer and your adviser.
- A lender workout: asking about a repayment plan, modification or other available arrangement.
- A conventional listing: marketing the property if the available time and likely proceeds support it.
- A direct sale: comparing a purchase proposal with the costs, timing and conditions of other options.
- A lender-approved short sale: seeking required lender approval when sale proceeds cannot cover the mortgage payoff.
- Professional help: consulting an attorney about notices and rights, or a HUD-approved housing counselor about mortgage options.
The Consumer Financial Protection Bureau’s mortgage-help resources explain how to find housing counseling. House For Cash offers property-purchase reviews; we do not provide legal advice, loan-modification services or foreclosure-rescue services.
Real House For Cash transactions
These completed purchases show different combinations of property condition, equity, occupancy and payment pressure. They do not establish the same foreclosure stage or outcome for every seller.
The seller was approximately three months behind on the mortgage. The home was otherwise in good condition, needing cleaning and minor maintenance. It sold as-is in October 2024; the case does not establish a particular foreclosure proceeding or lender agreement.
Nonpaying tenants and missed mortgage payments complicated a conventional sale. House For Cash purchased the rental as-is with the tenants still in place in August 2019. The case does not establish a particular foreclosure outcome.
After job loss, the seller was about seven months behind and had tried lender workouts and partial payments. The repair-needed home transferred as-is using existing financing, with the mortgage delinquency reinstated as a separate part of the transaction.
The seller had substantial equity but was about seven months behind on the mortgage, and the home needed significant repairs. An outright cash purchase closed in July 2024, with required obligations satisfied through closing.
This home had no mortgage and substantial equity. Unpaid HOA dues created pressure from the HOA and its attorney. The July 2024 sale illustrates a different obligation from mortgage debt; it does not establish that House For Cash stopped a foreclosure.
Equity and property condition are separate questions
Brannon shows payment pressure in a good-condition home. Dogwood shows mortgage delinquency despite substantial equity. The St. Petersburg case involved no mortgage at all. Repairs, equity, the type of obligation and available time each affect the choices.
If your home is market-ready, you have enough equity for normal selling costs and enough time to market and show it, listing with a real estate agent may better fit a goal of maximizing what the open market may pay. A direct sale may be more useful when repairs, tenant issues, constrained sale economics, time or convenience matter more. Compare the price, costs, contingencies and closing requirements. Read our broader guide to choosing a selling option.
How a property review works
- Share the property’s location, condition, occupancy and any known deadlines.
- We review whether a purchase may fit. Relevant payoff, title, approval and timing requirements need to be checked with the people handling the transaction.
- You compare the proposed terms with your alternatives. Any closing follows the agreement and its required conditions; there is no obligation to accept an offer.
Learn more about our purchase process.
Foreclosure Resources by State
Procedures and timelines vary by state and by the obligation involved. For a Florida property, explore our Florida foreclosure sale options. This national guide does not replace state-specific advice or review of your notices.
Frequently asked questions
Does requesting an offer stop foreclosure?
No. A request, offer or purchase agreement does not itself pause the process. Continue addressing notices and deadlines with your servicer and appropriate advisers.
Does a subject-to purchase cure missed payments?
No. Taking title subject to existing financing does not by itself cure a default, stop foreclosure or release the original borrower. Reinstatement is a separate action with its own requirements. The Inez example included reinstatement; that result should not be assumed for every existing-financing transaction.
What if the sale price will not cover what is owed?
Required payoffs, liens and closing obligations must be addressed. A lender-approved short sale may be necessary. Do not assume approval, forgiveness of remaining debt or a particular closing date.
How quickly can a sale close?
Timing depends on the agreement, title, required payoffs and approvals, and other closing conditions. We do not promise a fixed number of days or guarantee that a sale can beat a scheduled foreclosure sale.
Discuss whether a sale is practical
Share your property details for an individual, no-obligation review. You can also contact House For Cash. If a deadline is approaching, continue working with your servicer and appropriate professionals while exploring a sale.