A house does not need major repairs to be difficult to sell. If the remaining mortgage and other obligations are close to its likely sale price, the challenge may be the closing math. Start by estimating what a sale would actually leave you before deciding how to proceed.
What low equity means
Equity is the difference between a property’s value and the debt secured against it. Sale proceeds are a separate calculation: expenses and other amounts due at closing can reduce what the seller receives. A recent purchase financed with a small down payment may leave limited room for those costs.
An online estimate is not a payoff statement or a guaranteed sale price. Request current figures and compare realistic options for the property’s condition and market.
Work from an estimated closing statement
Gather the mortgage payoff for the expected closing date, any other liens, taxes or judgments, and an estimate of transaction costs. Compare those amounts with a realistic purchase offer or listing scenario. Ask the closing professional which items are estimates and which figures still need confirmation.
Do not assume that an agreement to cover closing costs also pays every debt against the property. With House For Cash, there are no real estate agent commissions, and House For Cash covers the seller’s customary closing costs. Mortgage payoffs, liens, taxes, judgments or other amounts owed against the property may still need to be paid from the closing proceeds.
Compare the available paths
List the property
A traditional listing may reach buyers who intend to live in the home. Consider likely price, time on market, preparation, commissions and other closing obligations together. A listing that has not sold may need a fresh assessment of price, condition and terms.
Consider a direct purchase
A direct buyer may offer a different combination of price, preparation requirements and timing. Compare estimated net proceeds and the written agreement, not just an advertised promise. A direct sale does not automatically solve an insufficient-payoff problem.
Bring cash to closing
If the shortfall is manageable and the closing requirements can be met, a seller may contribute funds to complete a sale. Confirm the amount and source requirements with the closing professional before committing.
Ask the lender about a short sale
A sale that leaves the mortgage unpaid in full may require lender approval, such as a short sale. Approval is not automatic. Review the lender’s written terms, including how any remaining debt is treated; do not assume that accepting sale proceeds releases every obligation.
Evaluate an existing-financing structure carefully
In a subject-to purchase, title transfers while the existing mortgage remains in place. The buyer agrees to make the payments, but the original borrower generally remains obligated unless the lender releases or replaces that obligation. This is not the same as paying the loan off at closing.
A due-on-sale clause may allow a lender to demand repayment following a transfer, subject to applicable law and exceptions. The seller also needs to understand payment-performance risk, how payments will be monitored, insurance arrangements, and the remedies in the agreement. Independent legal advice can help both parties assess the actual documents. A private purchase agreement does not bind the lender to release the borrower.
Subject-to is a specialized alternative, not a default recommendation for a low-equity seller. If a loan is already delinquent, transferring title subject to that loan does not itself cure the default or stop foreclosure.
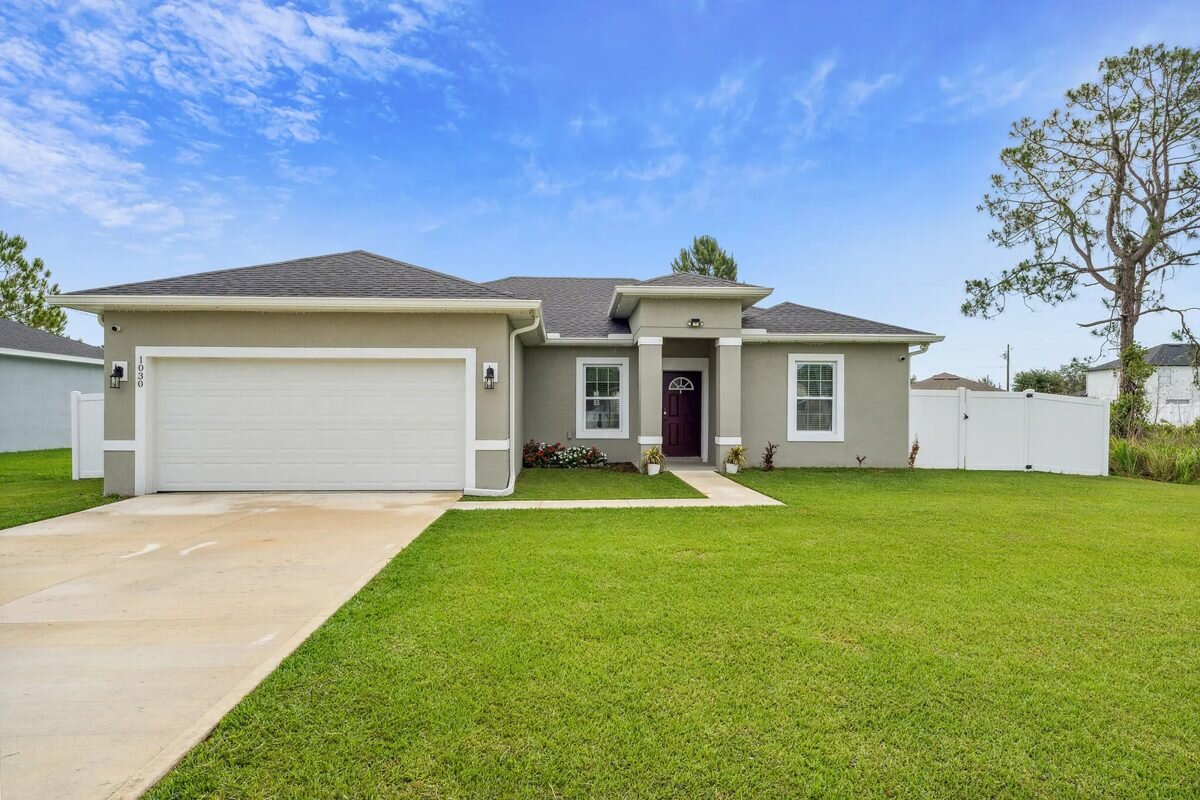
Real House For Cash example: 1030 James Dr
House For Cash purchased this Poinciana property on May 25, 2023. The home was only a few years old and in very good condition, with mostly cosmetic work needed. The seller had limited equity after a relatively recent financed purchase and needed to relocate back north for medical reasons. A traditional sale had been attempted for several months without success.
The property was purchased subject to existing financing. The seller received some cash, and the home was retained in the buyer’s rental portfolio. That does not establish that the lender released the seller from the original loan.
Read the James Drive case study or explore selling in Poinciana.
Questions to settle before signing
- What is the estimated net amount to the seller?
- Will the mortgage be paid off, modified, assumed with approval, or left in place?
- Who remains obligated to the lender after closing?
- Which approvals and closing conditions remain outstanding?
- What happens if the buyer does not perform?
Visit our Florida page and How It Works page to understand our process. You may request a no-obligation property review and compare any proposed terms with your alternatives.